Case study
How we helped a borrower in her mid-seventies buy a new home using her pension income.
Case summary:
Client type: Retired homeowner in her mid-70s
Mortgage purpose: Purchase of a bungalow
Property value: £170,000
Mortgage required: £40,000 at approximately 24% loan-to-value (LTV)
Income profile: State Pension, employer’s pension and private pension
Client preference: Independent borrowing without family assistance, a RIO or a lifetime mortgage
Main challenge: Securing a conventional mortgage in later life
Recommended mortgage product: Five-year fixed rate
The client
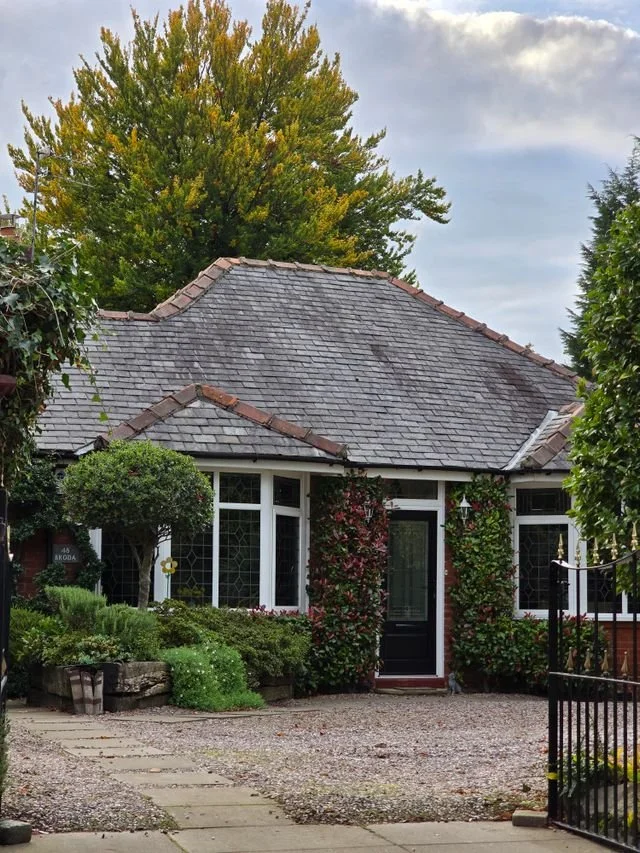
Our client was a retired homeowner in her mid-70s who had moved into a warden-controlled retirement village.
The move had not suited her, and she wanted to leave. She had found a bungalow where she could see herself settling permanently, but buying it would require a small mortgage.
The situation
Having thought her mortgage days were behind her, our client now found herself needing to upsize at a stage of life more commonly associated with downsizing.
The bungalow cost £170,000, and she needed £40,000 of borrowing to complete the purchase. She received a State Pension, an employer’s pension and a private pension, providing regular income to support the mortgage.
She wanted to arrange the purchase independently, without financial help from her children.
The later life lending challenge
The client’s age narrowed the choice of lenders, even though the mortgage represented a relatively small proportion of the property’s value.
We needed a lender whose age and mortgage term criteria could accommodate a borrower already in her mid-70s.
The substantial equity was helpful, but the lender still needed to be satisfied that her pension income could support the payments over an acceptable term.
The affordability challenge
Our client’s income came entirely from pensions.
The application needed to bring together her State Pension, employer’s pension and private pension, giving the lender a clear picture of the income available to meet her mortgage payments and everyday expenditure.
The borrowing also needed to feel manageable to her. With a fixed monthly income, certainty over the mortgage payment was an important part of choosing the right arrangement.
The mortgage choice challenge
Our client did not want a retirement interest-only mortgage or a lifetime mortgage.
She also did not want her children to contribute financially or join the borrowing. Her preference was to purchase the bungalow in her own name, using her own resources and pension income.
The task was therefore to find a conventional mortgage that met her circumstances and preferences, rather than assuming that her age required a specialist later life product or a family-assisted mortgage.
Our solution
We arranged a £40,000 mortgage towards the £170,000 bungalow purchase, with a lender able to accommodate her age and assess affordability using her pension income.
The application brought together all three pension sources to support borrowing in her sole name. This allowed her to proceed without involving her children in the mortgage or relying on their financial assistance.
We recommended a five-year fixed rate to provide stability. With her monthly income fixed, knowing what the mortgage would cost each month was particularly important.
The arrangement gave her predictable mortgage payments for the first five years as she settled into her new home.
Our client’s outcome
Our client was able to leave a retirement setting that had not suited her and purchase a bungalow she had chosen as her long-term home.
The £40,000 mortgage bridged the gap between her available funds and the purchase price, allowing her to make the move independently.
She secured the borrowing without a RIO, a lifetime mortgage or financial help from her children, with payment certainty for the first five years.
Frequently asked questions.
Every client and every mortgage is different, but there are some questions we are asked regularly.
From affordability and deposits to complex income, expat mortgages and specialist property finance, our FAQs explain how different lenders may approach different circumstances.
Find out more….
See how we’ve helped….