
Specialist buy-to-let mortgages:
Mixed-used & semi-commercial properties
“Mixed-use” and “semi-commercial” are sometimes used interchangeably, but they can describe different mortgage requirements. One lender may treat a property as specialist residential lending, while another regards it as commercial.
The balance between residential and business use can determine how the case is treated, which products are available and the maximum loan-to-value.
Mixed-use properties
A mixed-use property generally combines the borrower’s home with land, buildings or space used to operate a business or generate income.
Examples include:
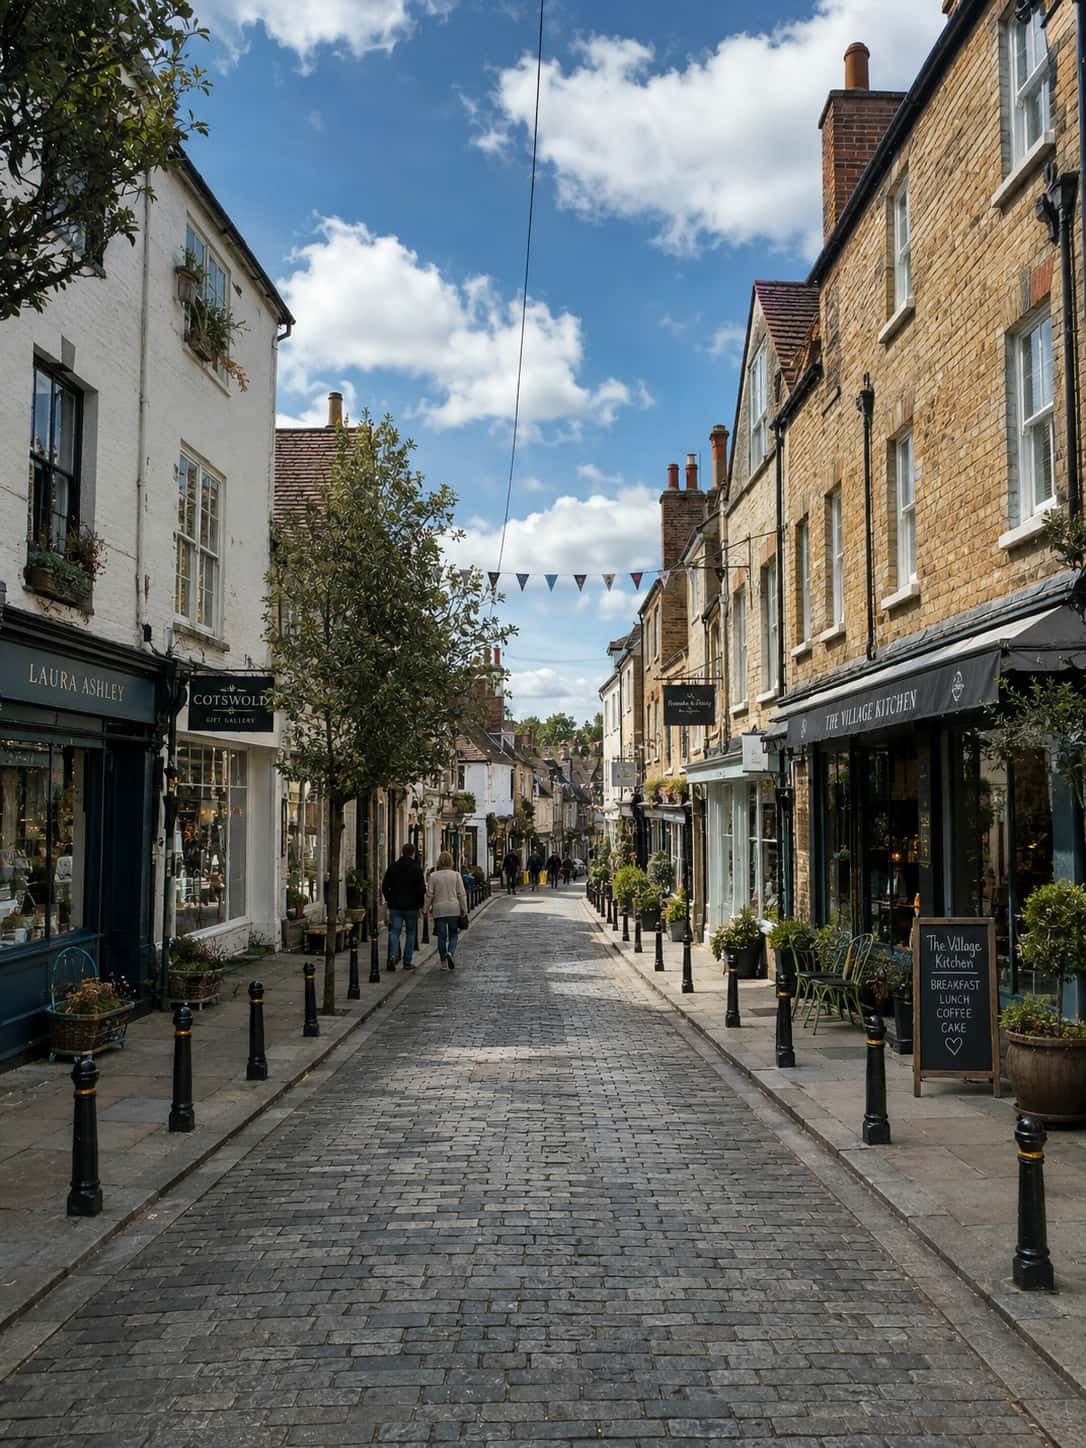
A shop with the owner’s accommodation above
A house with consulting rooms, a salon or veterinary practice
A home with kennels, a cattery or equestrian facilities
A workshop or office beside the main house
A property with holiday cottages
A pub or restaurant with owners’ accommodation
The lender will consider how much of the property is used as the borrower’s main residence and whether the business activity is ancillary to the home or central to the purchase.
Different lenders, different classifications
Some specialist building societies offer residential mixed-use mortgages where the home represents a sufficient proportion of the property. Another lender could treat the same property as owner-occupied commercial premises and assess the business’s profitability and cash flow.
The residential-to-business ratio may be measured by floor area, land, value, income or a combination of these. Lenders apply different thresholds.
As the commercial proportion increases, the case may move into a different product range, attract higher pricing or be subject to a lower maximum loan-to-value. “Mixed-use” should therefore be treated as a broad property description rather than a precise mortgage category.
Semi-commercial properties
A semi-commercial investment property normally contains residential and commercial accommodation let to third parties. Examples include a shop with a flat above, offices with residential units or a restaurant beneath several flats.
Where the complete property is held on one title, it will normally require a semi-commercial mortgage. A separately titled flat may instead qualify for an ordinary buy-to-let mortgage.
See Mortgages for flats above commercial premises for more detail.
The balance of residential and commercial use
The proportion of each use remains important within semi-commercial lending. A mostly residential building with a small shop may be treated differently from a property whose value and income depend primarily on a restaurant, pub or other commercial tenant.
The ratio can influence lender choice, pricing, loan-to-value, rental coverage requirements and the type of valuation required. Lenders may also consider each element separately rather than relying solely on the combined rent and value.
Specialist semi-commercial finance
Semi-commercial mortgages are generally provided by specialist banks, commercial lenders and niche non-regulated lenders. Where the property is acquired wholly for business or investment purposes, the lending will usually fall outside residential mortgage regulation.
Rates and arrangement fees are typically higher than for conventional residential or buy-to-let mortgages. A specialist commercial valuation will normally be required, and a larger deposit may be necessary.
An experienced specialist mortgage broker can establish how different lenders will classify the property and which type of finance provides the appropriate route.