Case study
How we helped a couple in Bermuda fund a £1.7m self-build project in Winchester.
Case summary
Client type: British expatriates in Bermuda
Income currency: US dollars (USD)
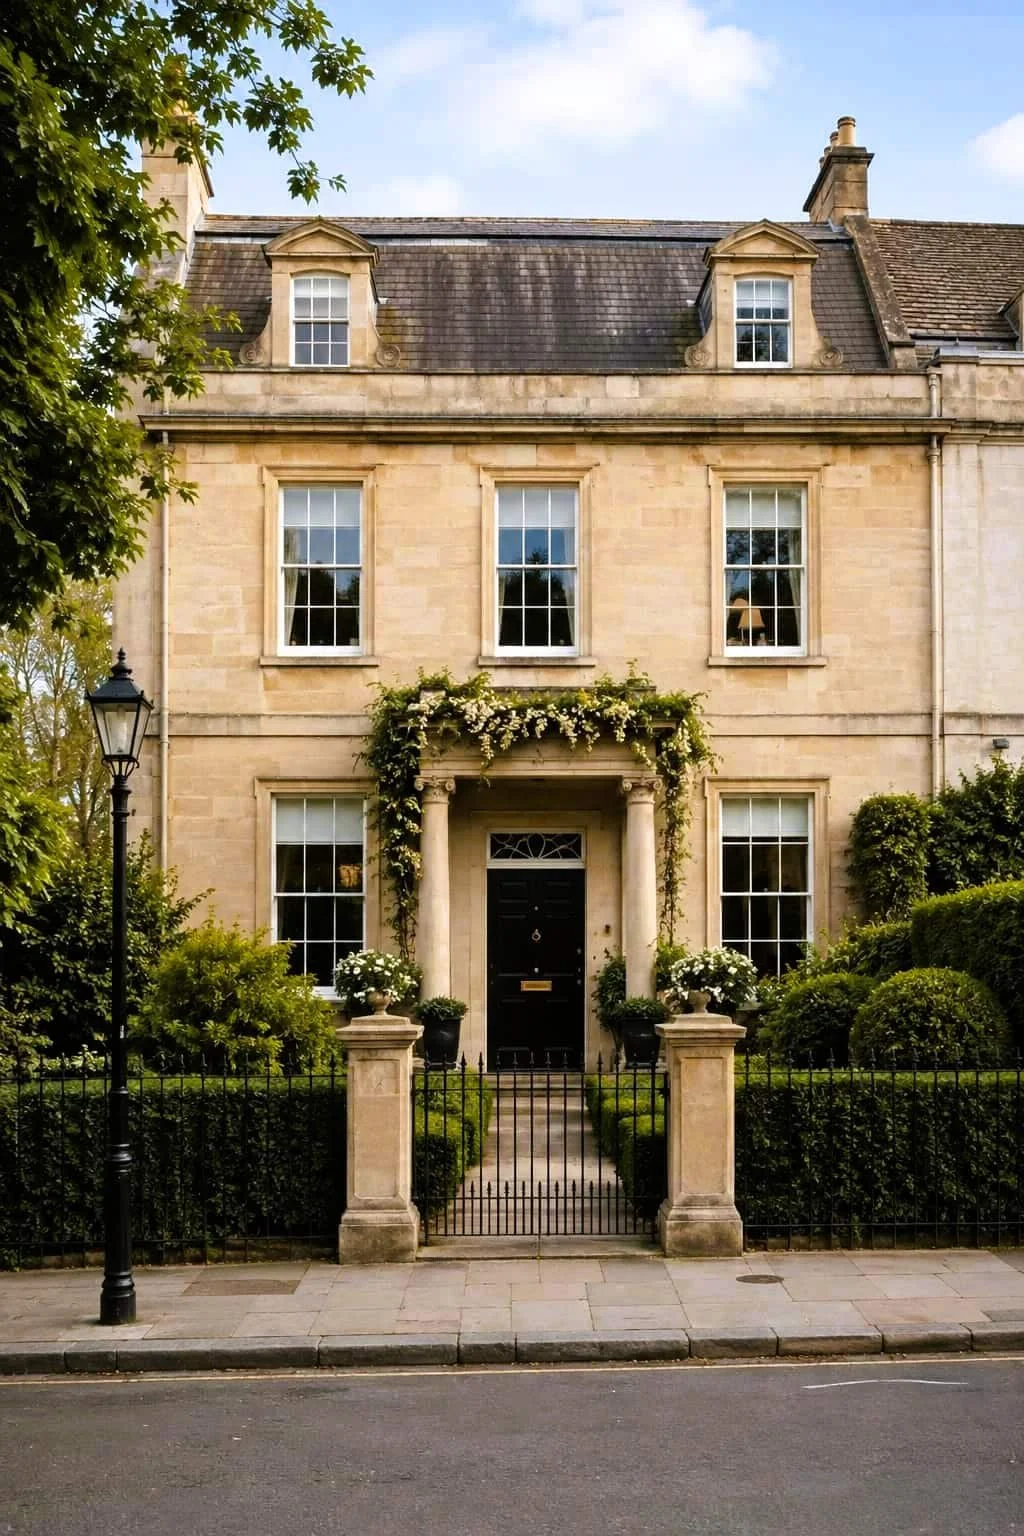
Project: Demolition and rebuild of a home in Winchester
Intended use: UK base initially; main residence in the future
Anticipated completed value: £3m
Exit strategy: Agreed refinance onto an expat residential mortgage
Main challenge: Large expat self-build mortgage
Finance arranged: £1.7m regulated development facility with monthly drawdowns
The client
Our clients were UK nationals who were living in Bermuda.
Both worked in the island’s insurance and reinsurance sector and received their employment income in US dollars. They wanted to build their dream home in Winchester, creating a UK base they could use while living overseas and eventually occupy as their main residence.
The situation
The clients’ Bermuda residency significantly restricted the available self-build lenders.
Although both had employment income, the lender needed to accept applicants living overseas, earning in US dollars and building a property they would initially use as a UK base.
The proposed future move into the property did not change their circumstances at the time of application. The funding needed to work while they remained resident in Bermuda.
The income challenge
The couple's income was earned in US Dollars while living in Bermuda.
The lender needed to assess overseas employment, foreign currency income and affordability using income generated outside the UK, with each lender applying its own criteria.
The loan size challenge
The only UK self-build lender we identified that could consider expatriates living in Bermuda could not accommodate the £1.7m borrowing requirement.
This left a gap between an acceptable borrower profile and the lender’s maximum loan size. The project’s anticipated £3m end value did not resolve that restriction.
We therefore needed an alternative form of construction funding that could support the scale of the project and its intended residential use.
The staged-funding challenge
The clients had already committed their own money to the early stages, but needed the facility to fund the continuing contractor costs.
A loan available only once the house was finished would not meet that need. The funding had to be accessible during construction, with monthly drawdowns supporting the programme of works.
The timing of those releases was therefore an important part of the arrangement, alongside the total facility amount.
The exit-strategy challenge
Development finance would fund the construction, but it was not intended to remain in place as the clients’ long-term mortgage.
The exit needed to accommodate the completed property, the required borrowing and the clients’ continuing Bermuda residency and US-dollar earnings.
It was therefore important to establish the route onto an expat residential mortgage at the outset, rather than leave that question until the development facility approached repayment.
Our solution
We arranged a £1.7m regulated development facility to fund the remaining construction costs.
This provided an alternative to the self-build mortgage route, where the combination of Bermuda residency and loan size had prevented a suitable arrangement.
The facility was structured to begin releasing funds in monthly tranches to cover contractor costs, following the clients’ initial investment in the project.
Alongside the construction funding, we agreed an exit onto an expat term residential mortgage. This connected the immediate funding requirement with the clients’ longer-term plans for the property.
Our clients’ outcome
The clients secured access to a £1.7m facility to continue building their Winchester home, with monthly drawdowns supporting the remaining works.
An agreed residential mortgage exit provided a route beyond the construction phase, accommodating their intention to use the finished property as a UK base before making it their main residence.
By considering the construction finance and eventual mortgage together, we found a workable structure for a project that fell outside the available self-build lending options.
Frequently asked questions.
Every client and every mortgage is different, but there are some questions we are asked regularly.
From affordability and deposits to complex income, expat mortgages and specialist property finance, our FAQs explain how different lenders may approach different circumstances.
Find out more….
Read our perspective….