
Case study
How we helped refinance a period holiday let in Southwold through a limited company.
Case summary:
Client type: portfolio landlords
Location: Southwold, Suffolk
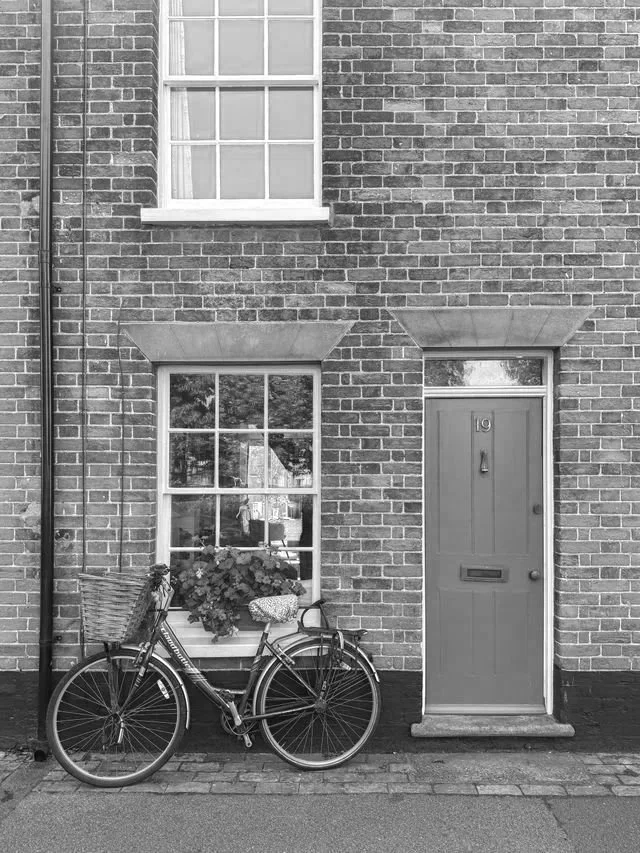
Property type: Mid-19th century period home
Planning context: Within an Article 4 area
Intended use: Holiday let accommodation
Ownership structure: Limited company SPV
Main challenge: Limited company holiday let
Mortgage arranged: Specialist holiday let remortgage
The client:
Our client wanted to refinance a holiday-let property in the coastal town of Southwold, with the borrowing arranged through a limited company special purpose vehicle.
The property dated from the mid-19th century and was situated within an Article 4 area.Our client wanted to refinance a holiday-let property in the coastal town of Southwold, with the borrowing arranged through a limited company special purpose vehicle.
The property dated from the mid-19th century and was situated within an Article 4 area.
The situation:
The remortgage required a lender comfortable with both holiday letting and limited company borrowing.
Although each is familiar within specialist property lending, the combination is less widely accepted. The property’s age and local planning context added further considerations when identifying a suitable lender.
The task was therefore to find a mortgage that accommodated the complete circumstances, rather than a lender whose criteria matched only part of the case.
The ownership challenge:
The property was owned through a limited company SPV, which narrowed the available options.
Lenders offering limited company buy-to-let mortgages do not necessarily accept holiday lets. Equally, a lender willing to finance holiday accommodation may restrict that lending to personal ownership.
We needed a lender comfortable with both elements from the outset.
The property challenge:
The property was built in the mid-19th century and, although not listed, was located within an Article 4 area.
Its age and planning context needed to be considered alongside its holiday-let use. The relevant question was what the local direction covered and whether it had any bearing on the property or transaction, not simply whether an Article 4 designation existed.
The holiday let challenge:
The property’s use as holiday accommodation was central to the lender selection.
It needed to be assessed as a holiday let, with an appropriate approach to rental income and affordability, rather than treated as a conventional property let on a long-term tenancy.
Finding a lender that accepted this use was only the first step; its lending approach also needed to work for the proposed SPV borrowing.
Our solution:
Our approach centred on the combination of holiday-let use, limited company borrowing and the property’s individual characteristics.
We focused lender selection on those able to accommodate holiday lets within an SPV, rather than relying on general limited company buy-to-let criteria.
The property’s age and Article 4 location formed part of the case presented for consideration, alongside the borrowing structure and letting arrangements. This gave the lender a clear picture of the transaction and the matters relevant to its assessment.
Our client’s outcome:
We successfully arranged the holiday-let remortgage through a limited company SPV.
The result demonstrates why lender selection matters in specialist property finance. Holiday letting and company borrowing may each be acceptable separately, but securing a mortgage depends on finding a lender comfortable with them together, and with the property itself.